Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance
Bitcoin Magazine Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance From digital ownership to borderless value,…
Japan’s October 6 auction drew firmer demand at a higher yield after earlier foreign-debt sales, raising a potential Bitcoin financing risk. The post As Japanese institutions sell ¥2.6 trillion in…
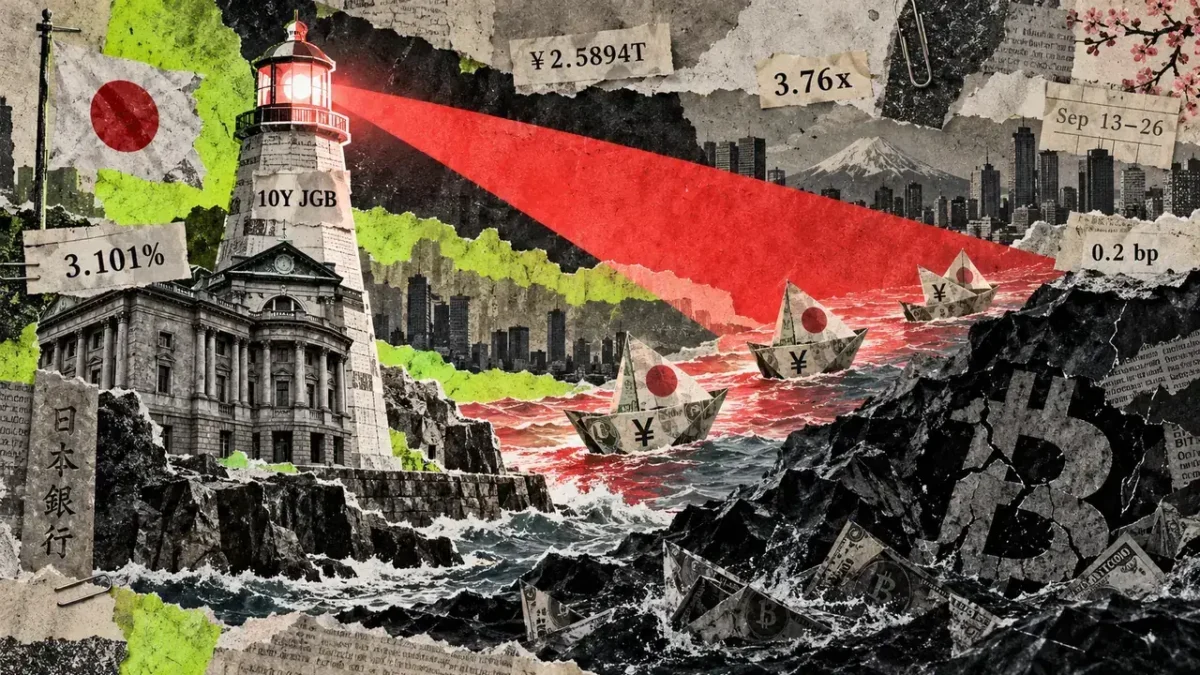
Japan’s October 6, 2026 auction of ten-year government bonds attracted more competitive demand relative to the debt sold, even as its average yield rose to 3.101%. For Bitcoin, higher returns on Japanese debt raise a question about how a sustained shift in bond allocation could affect global financing.
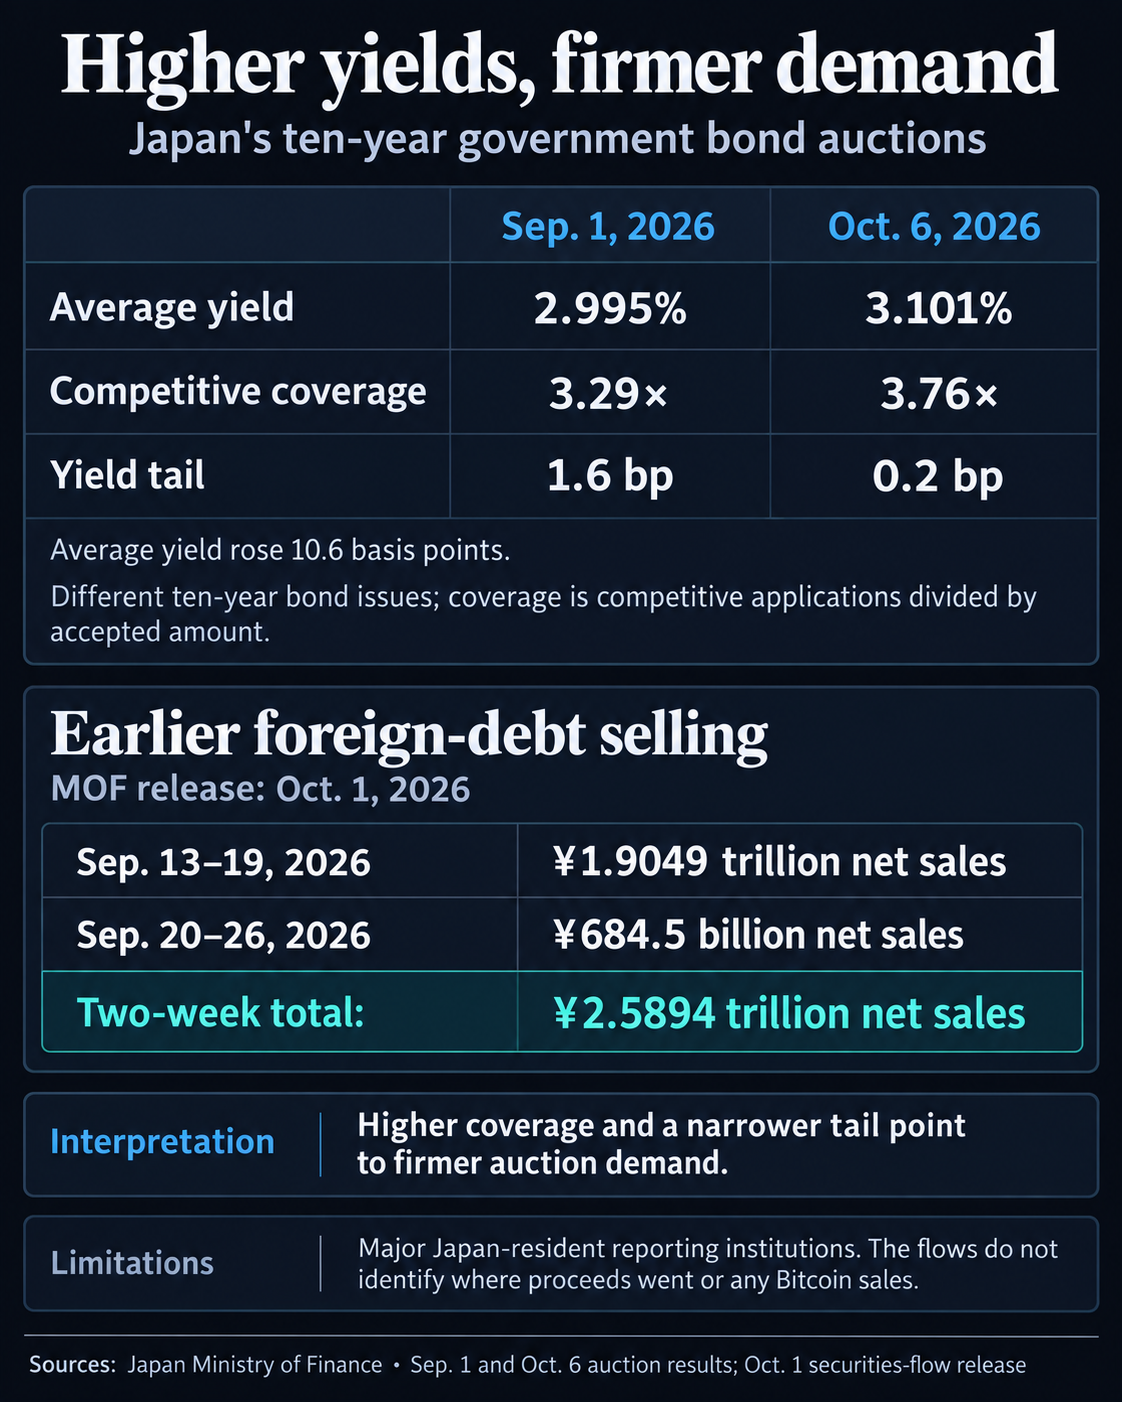
The Ministry of Finance’s result put the average yield up from 2.995% at the September 1 sale, an increase of 10.6 basis points. Competitive auction coverage, the amount sought by participants divided by the amount accepted, rose from about 3.29 times to 3.76 times.
The yield tail narrowed from 1.6 to 0.2 basis points. That gap measures the yield at the lowest accepted price against the average yield. Alongside the higher coverage, the smaller tail points to firmer demand at the higher yield.
Related Reading
The backdrop is two earlier weeks of foreign-debt selling. MOF’s October 1 flow release recorded net long-term debt sales of ¥1.9049 trillion during September 13–19 and ¥684.5 billion during September 20–26. Together, those weekly observations amount to net sales of ¥2.5894 trillion.
The series covers designated major Japan-resident reporting institutions and classifies foreign securities by issuer residence. It does not identify US Treasury sales, currency conversion, reinvestment into Japanese government bonds or Bitcoin transactions.
If Japanese institutions persistently prefer domestic bonds over overseas debt, reduced foreign bond demand could raise borrowing costs and weigh on capital available for risk-taking.
Related Reading
The authors of a Bank for International Settlements working paper identify global funding conditions and speculative motives as important drivers of cross-border Bitcoin and Ether flows. Their 2017 to mid-2024 sample supports the relevance of funding conditions to crypto flows.
Institutional portfolio allocation also differs from leveraged yen carry trades, which involve positions financed with borrowed yen. A ten-year auction yield does not measure the short-term cost of that borrowing. In their August 2024 analysis, BIS researchers described how deleveraging and margin increases amplified that month’s market turbulence. It illustrates how financing stress can spread across markets, without demonstrating a current unwind.
Related Reading
The next useful evidence is whether foreign-debt selling continues alongside independently observed funding stress. That pattern would be consistent with the proposed Bitcoin financing channel; renewed buying and calm funding would weaken the interpretation.
Bitcoin Magazine Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance From digital ownership to borderless value,…
Managing your crypto taxes can become increasingly complicated as your activity starts spreading across multiple exchanges, wallets, blockchains, and DeFi protocols. CoinTracking…
Here's how investors are rapidly changing the way they seek exposure to major assets.
Eight of 13 cash sessions fell from September 21–October 7, 2026, but boundary checks and opposing ETF flows leave sustained institutional selling…