Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance
Bitcoin Magazine Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance From digital ownership to borderless value,…
Comparable single-security or narrow-index contracts outside the joint listing regime would move under SEC oversight. The post FalconX asks SEC to bring single-stock perpetuals from DeFi under swap rules appeared…
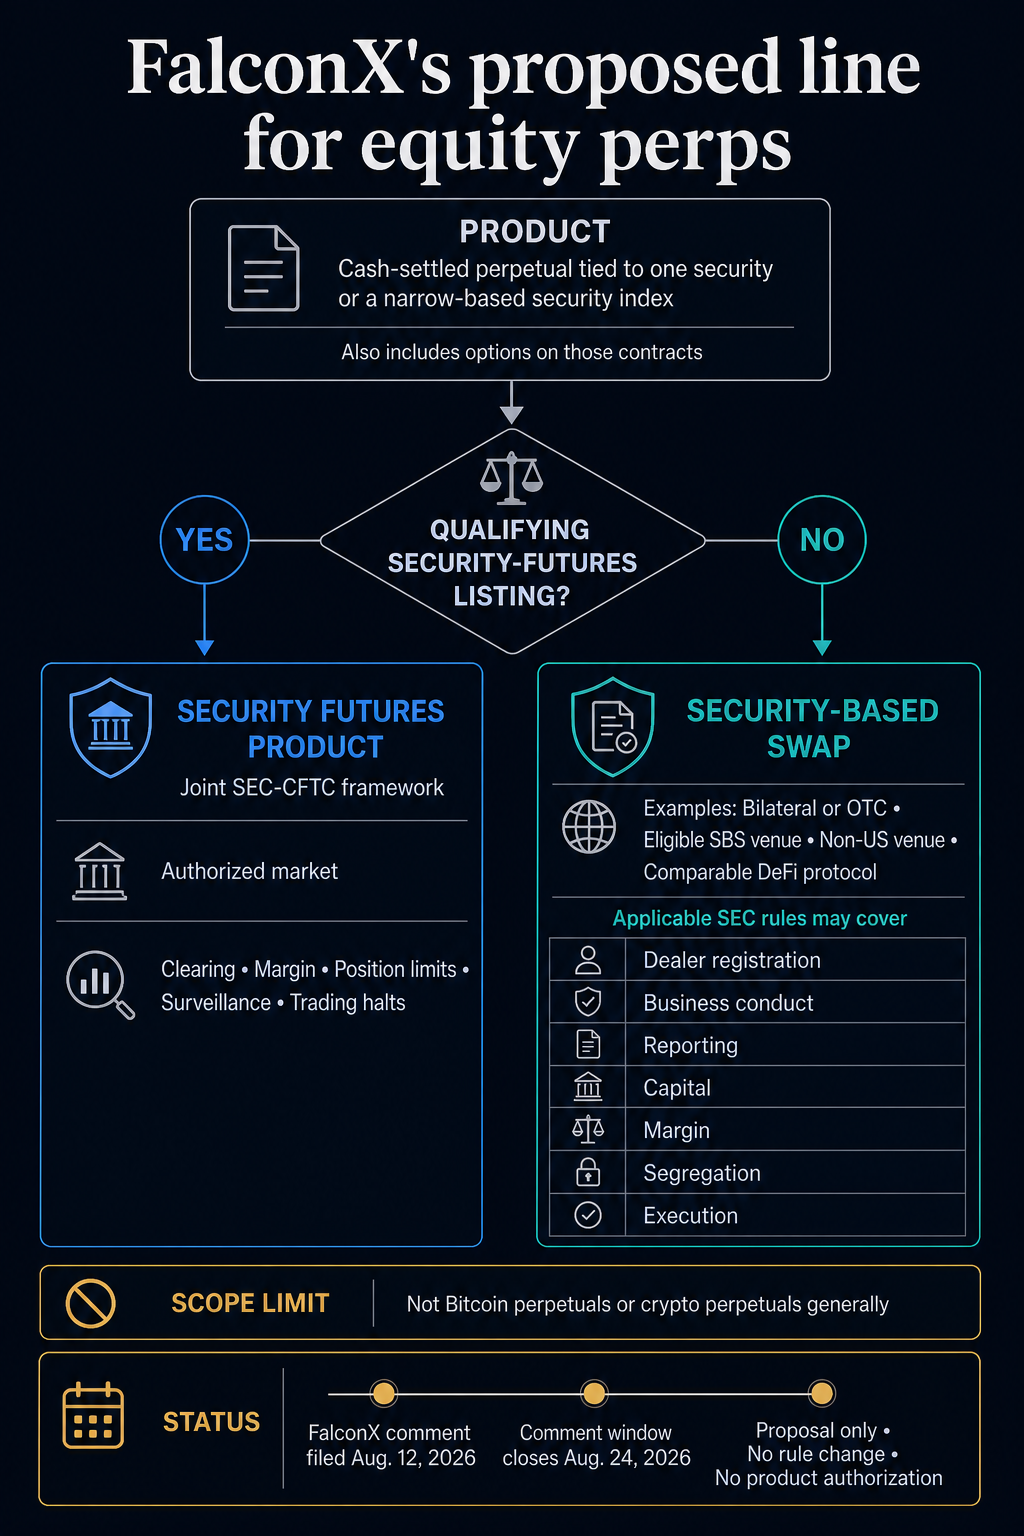
FalconX Bravo wants US regulators to treat cash-settled perpetuals tied to a single security or a narrow-based security index as security-based swaps under SEC rules when they fall outside the joint SEC-CFTC security-futures framework.
The filing expressly includes comparable contracts offered through DeFi protocols.
The firm submitted its proposal to the Securities and Exchange Commission and Commodity Futures Trading Commission on Aug. 12. FalconX Bravo is listed on the CFTC’s registered swap dealer roster and describes its business as focused on digital assets and digital asset market participants.
FalconX’s definition covers the specified perpetuals and options on them. It does not extend to Bitcoin perpetuals or crypto perpetuals generally.
A qualifying contract listed as a security futures product on a market authorized by both agencies stays in the joint regime. That route carries listing and market safeguards covering the underlying security or index, clearing, margin, position limits, surveillance, and trading halts.
FalconX examples include bilateral and over-the-counter transactions, contracts offered by eligible venues or platforms authorized for security-based swaps, non-US venues, and comparable DeFi protocols.
Related Reading
For affected dealers, SEC treatment can trigger registration, business-conduct, transaction-reporting, capital, margin, and segregation requirements. A platform may also come within the security-based swap execution framework, depending on its structure and any applicable execution or clearing mandate.
Dealer status and other duties depend on the participant and transaction, so classification would not automatically require every protocol developer or trader to register.
FalconX also asks the SEC to reduce duplicated requirements for firms already overseen by the CFTC. The requested amendment to Rule 18a-10 raises its combined-notional threshold for alternative compliance from 10% to 49%. FalconX keeps the fixed-dollar cap, SEC registration and oversight, and requirements not covered by the relief.
The CFTC’s June policy statement reserved other asset classes for separate review and identified equity and narrow-index products as distinct regulatory questions.
A comment filed Aug. 21 by independent researcher Amadeus Brandes recommended the existing mixed-swap process, with protections addressing insider information, manipulation, leverage and funding-rate risks.
The comment window closes Aug. 24. The agencies have FalconX’s listed-versus-unlisted test and Brandes’ mixed-swap alternative before them, but neither submission is agency policy. Closing the docket changes no jurisdictional rule, authorizes no product, and does not commit either regulator to rulemaking.
Bitcoin Magazine Money20/20 USA 2026: How Bitcoin, Stablecoins and AI Are Reshaping the Future of Finance From digital ownership to borderless value,…
Managing your crypto taxes can become increasingly complicated as your activity starts spreading across multiple exchanges, wallets, blockchains, and DeFi protocols. CoinTracking…
Here's how investors are rapidly changing the way they seek exposure to major assets.
Eight of 13 cash sessions fell from September 21–October 7, 2026, but boundary checks and opposing ETF flows leave sustained institutional selling…