Mantle adds Paxos’ USDG stablecoin, joins Global Dollar Network
Mantle has added Paxos-issued USDG as a natively minted stablecoin while joining the network’s reward-sharing structure.
The 41,252.1 BTC CME position dwarfs Coinbase's 151.62 BTC residual, while any hedge leg could offset a squeeze. The post Massive Bitcoin derivatives gap between CME and Coinbase threatens violent…
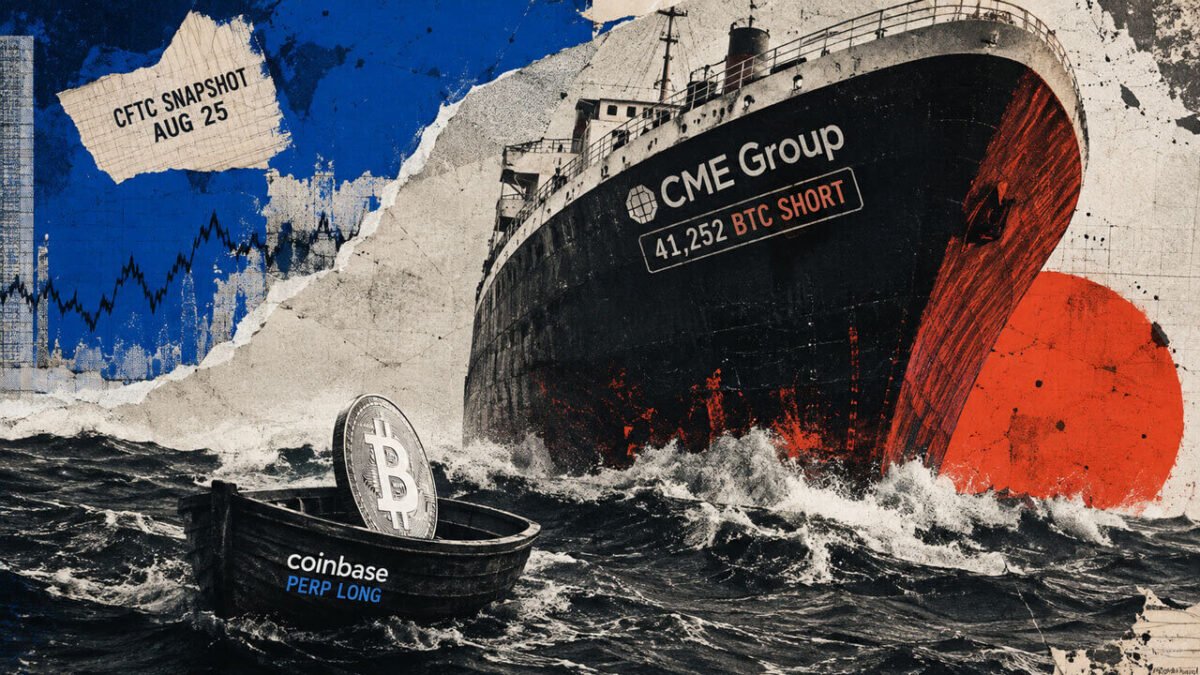
Leveraged funds held a 41,252 BTC-equivalent net short across CME Bitcoin futures, including standard and Micro contracts on Aug. 25, while the CFTC snapshot showed the same category net long just 151 BTC in Coinbase’s nano Bitcoin perpetual-style contract.
For the next forced unwind, the important distinction is scale rather than an evenly matched directional split. The report showed 118,267 BTC-equivalent of open interest across the two CME products, compared with 2,322 BTC on Coinbase. CME was about 51 times larger by that measure, and its leveraged-fund net short was roughly 272 times the magnitude of Coinbase’s net long.
A standard CME Bitcoin futures contract represents 5 BTC and a Micro Bitcoin futures contract represents 0.1 BTC, according to CME’s specifications. Leveraged funds were net short 8,114 standard contracts, or 40,570 BTC, and 6,821 micro contracts, or 682.1 BTC.
Each Coinbase nano perpetual-style contract represents 0.01 BTC. The category’s 15,162-contract net long therefore equaled 151 BTC, which is the residual between 1,195 BTC-equivalent of gross longs and 1,043 BTC-equivalent of gross shorts.
CME positioning also became materially more net short during the week. From Aug. 18 to Aug. 25, the standard-contract net shifted 3,295 BTC further short and the micro net moved 777 BTC further short, a combined bearish change in net positioning of 4,072 BTC.
Related Reading
That change still cannot safely be called an outright bearish wager. The CFTC’s category notes do not connect reported futures accounts to spot Bitcoin, exchange-traded fund holdings, or cross-venue hedges. Without matched Aug. 25 readings for CME basis and Coinbase funding, the snapshot cannot distinguish directional shorts from cash-and-carry trades or other hedges.
If CME shorts are uncovered directional positions, a squeeze would force futures buying through a pool far larger than Coinbase’s current net long. If they are basis trades, closing them would pair futures buying with the sale of spot Bitcoin or ETF exposure, the same two-legged structure described in cash-and-carry analysis. That sale could offset part of the price effect even as the reported short contracts.
Coinbase can still generate venue-specific liquidations, a risk built into perpetual-style markets, but the 151 BTC net figure reveals neither gross leverage nor liquidation thresholds. Its small size cannot counterbalance the much larger CME position by itself.
Related Reading
ETF flows reinforce the timing limit. Farside data show US spot Bitcoin ETFs absorbed $1.12 billion from Aug. 24 through Aug. 27, then lost $201 million on Aug. 28. The five sessions remained net positive by $924 million, but the CFTC snapshot was fixed on Aug. 25 and cannot reflect the later inflows or Friday’s reversal.
Related Reading
A clearer unwind signal would combine the next CFTC position change with matched CME basis, Coinbase funding, and ETF flows. Until then, the mismatch shows where the larger exposure sits, not whether it is a naked bet or one leg of a hedge.
Mantle has added Paxos-issued USDG as a natively minted stablecoin while joining the network’s reward-sharing structure.
The model can independently discover and exploit unknown security flaws across hardened systems, triggering a staged rollout and White House review before…
Kalshi previously said it had been placed in an “impossible position” after federal authorities directed the company to ignore a Michigan restraining…
House Republicans’ decision to cut the September legislative session short could significantly delay the CLARITY Act.